US consumer sentiment spent the opening stretch of 2026 in a holding pattern: not collapsing, not recovering, and split sharply by income. McKinsey’s ConsumerWise research, tracking how households feel about the economy and where they intend to spend, found confidence in early 2026 broadly flat against late 2025 — with a smaller share of consumers describing themselves as pessimistic and slightly more landing in neutral or mixed territory.
Income remains the single strongest dividing line. The wealthier the household, the more optimistic the outlook its members report. Generational differences exist but are weaker: baby boomers carried the largest share of pessimists, followed by Gen X and Gen Z, while millennials posted the largest share of optimists.
Spending intentions followed familiar first-quarter seasonality with a few telling bright spots. Net spending intent — the balance between people planning to spend more and people planning to spend less — stayed negative across discretionary categories and softened in several, the usual post-holiday pattern. But intent rose for home improvement and gardening supplies, up 11 percentage points against the fourth quarter of 2025, and for domestic flights, up five points, with further gains across short-term rentals, hotel stays and entertainment away from home.
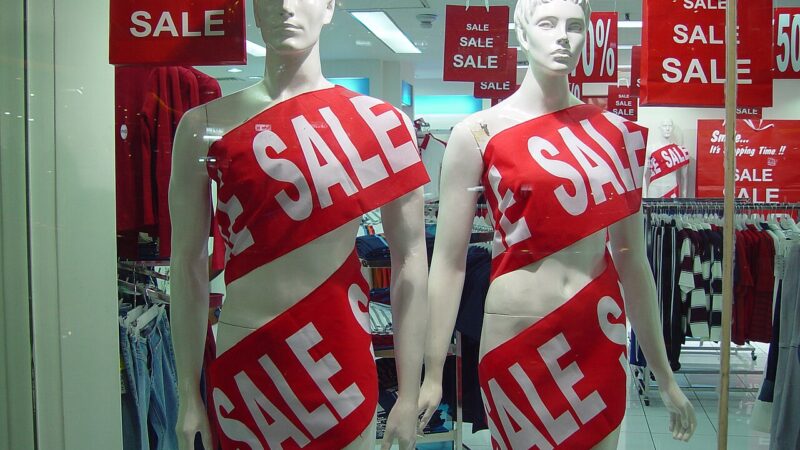
McKinsey’s overall characterisation is of consumers spending selectively rather than retreating across the board — protecting experiences and home projects while trimming elsewhere. That selectivity shows up consistently in this year’s other consumer evidence: PwC’s holiday research found travel budgets cut while gift spending held nearly flat, and the ICSC’s intentions survey found shoppers switching brands and trading down on products rather than abandoning the holiday altogether.
For marketers, the flat-but-split sentiment picture has practical consequences. Aggregate confidence numbers conceal the operative reality: premium and value segments are living in different economies. WARC’s latest advertising forecast makes the same point from the spending side — global ad budgets are growing 11.9 percent in a year of weak consumer confidence, a contradiction it attributes to growth concentrating in AI-exposed sectors and higher-income households.
The strategic response most brands are converging on is precision: value messaging and entry price points where households are squeezed; experience, quality and service where they are not; and flexible media that can be reweighted as sentiment moves. McKinsey’s data suggests there is no single 2026 consumer to address. On Friday, October 9, 2026, there are at least two — and they are reading different headlines about the same economy.
Related reading: NWSL Bets Its Marketing on the World Cup Spotlight · The Average Engagement Rate Is Misleading Brands, Data Shows · Shoppers Trust AI to Advise Them — Just Not to Buy for Them